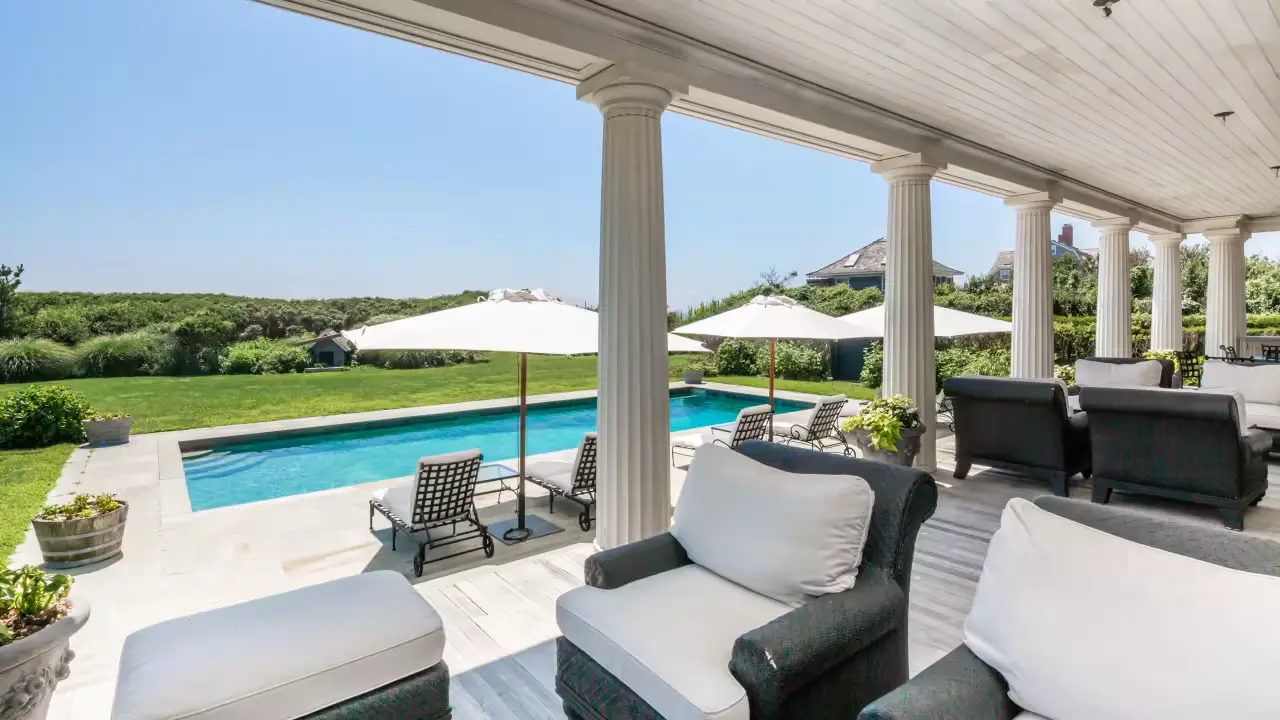
A waterfront second home in Southampton can offer beach days, boating access, bay views, and a reliable place to gather with family. It can also involve questions that do not show up in listing photos, including shoreline rights, flood exposure, seasonal upkeep, permits, insurance, and the practical realities of arriving on a busy summer weekend.
Before comparing houses, buyers can benefit from the local context. Southampton real estate agent Harald Grant and the team at Harald Grant Real Estate focus on Hamptons homes, rentals, landmark sales, and neighborhood coverage from Southampton through communities such as East Hampton, Sag Harbor, Bridgehampton, Water Mill, and Montauk. That on-the-ground familiarity can help buyers ask better questions about how a waterfront setting, access route, and property type fit their goals.
The View Is Only One Part of the Purchase
Waterfront properties often create a strong first impression, but the biggest house or widest water view is not automatically the strongest choice. A useful approach is to evaluate every candidate’s home with the same checklist. That keeps a beautiful setting from overshadowing ownership costs, maintenance demands, or limitations that could affect enjoyment later.
Define How You Will Use the Home
Start with a realistic description of the home’s role. A weekend retreat has different needs from a future full-time residence or a home intended for occasional rentals. Consider how many weeks you expect to occupy it, whether guests need separate bedrooms and outdoor gathering areas, and whether the house will be vacant during colder months.
- Weekend escape: Prioritize an easy trip, manageable upkeep, and a layout that feels comfortable without a large household.
- Seasonal family home: Consider the number of bedrooms, storage, parking, outdoor living space, and access to beaches or village amenities.
- Future retirement home: Test everyday convenience, including grocery access, medical services, stairs, bathrooms, and year-round comfort.
- Part-time rental property: Review local rules, insurance terms, lender requirements, and the work involved in managing guests.
Compare Location Before Finishes
A renovated kitchen can be changed. The surrounding location cannot. Compare travel time from your primary home, the route to beaches and marinas, proximity to restaurants and shops, and access to rail or airports if those matter to your household. Also drive the route on a summer weekend and return in the off-season. A property that feels lively in July may feel very different when the weather changes and fewer services are open.
For each home, take a short real-life test. Drive to a grocery store, check mobile reception and internet options, listen for road or marina noise, and imagine the home during a rainy November week rather than only on a sunny showing day.
Confirm What “Waterfront” Actually Includes
Waterfront does not automatically mean private beach ownership, a permitted dock, deep-water boating access, or unrestricted use of the shoreline. Ask for the deed, survey, and any documents that describe easements, shared access, dock rights, mooring rights, or maintenance obligations. If there is a bulkhead, seawall, pier, or dock, confirm its condition and whether permits are available.
Shoreline work can involve state and local review. New York’s coastal erosion management permit program identifies docks, bulkheads, seawalls, and similar shoreline structures among the activities that may require permits. Buyers should have an attorney, an inspector, or a qualified shoreline professional review the records before assuming that a structure can be repaired, enlarged, or replaced in the same way.
Review Flood Exposure, Elevation, and Drainage
Check flood information before making an offer, not after financing is underway. The FEMA Flood Map Service Center allows buyers to look up official flood hazard information by address. Ask whether an elevation certificate is available, request records of prior water intrusion when available, and inspect lower levels, crawl spaces, foundation areas, sump equipment, grading, and drainage.
A mapped flood zone is one part of the picture. The home’s elevation, construction, drainage, nearby road conditions, and insurance options should all be reviewed together. Ask how the property and surrounding utilities performed during significant storms.
Build a Complete Ownership Budget
The purchase price is only the starting point. Request real quotes and estimates during the inspection period for homeowners, flood, wind, or specialty insurance; property taxes; utilities; pool care; landscaping; security; home-watch services; dock or shoreline maintenance; and association or private-road fees. Salt air, wind, moisture, and sand can make exterior maintenance especially important for homes near the water.
Understand Financing and Rental Plans
Second-home financing can differ from financing for a primary residence. Lenders may evaluate occupancy plans, reserves, down payment, and whether rental income will be part of the transaction. A home used heavily for rentals may be treated differently from a personal second home. Speak with at least two lenders early, and give each one an accurate description of how you expect to use the property.
Inspect for Coastal Wear
Use a general inspection as a starting point, then add specialists when the property calls for them. Give particular attention to the roof, flashing, windows, doors, siding, exterior fasteners, decks, railings, HVAC equipment, dehumidification, foundation, septic system, well, dock, bulkhead, retaining wall, and drainage. A specialist can provide a more useful opinion on a seawall, dock, or septic system than a standard inspection alone.
Use a Simple Tour Scorecard
After each showing, score the home from one to five in these categories:
- Location: Does it work in every season and for your normal travel routine?
- Water access: Are beach, dock, mooring, and shoreline rights clear?
- Condition: What requires repair now, and what may need attention within several years?
- Insurance: Is appropriate coverage available at a cost you can carry comfortably?
- Annual cost: Have you included taxes, utilities, maintenance, and services?
- Resale appeal: Will a future buyer understand the same advantages and limitations?
A smaller, easier-to-maintain home with reliable access may prove more enjoyable than a larger estate that sits empty and requires constant oversight.
Common Buyer Questions
Is a waterfront second home a good investment?
It depends on the purchase terms, carrying costs, condition, intended use, and future buyer demand. Enjoyment and long-term fit should be central to the decision, rather than relying on assumptions about appreciation or rental income.
Should insurance quotes come before an offer?
Yes. Early quotes can reveal coverage limits, deductibles, and costs that affect both affordability and financing.
Is a dock included with the property?
Do not rely on the listing description alone. Confirm ownership, access, permits, condition, and maintenance responsibilities through the deed, survey, records, and inspections.
Final Pre-Offer Checklist
- Confirm your intended use and realistic occupancy schedule.
- Visit the location at more than one time of year.
- Review flood information, elevation details, and drainage.
- Obtain insurance estimates before contingencies expire.
- Verify waterfront, beach, dock, and access rights.
- Estimate all annual carrying and maintenance costs.
- Confirm financing terms and rental restrictions.
- Order specialist inspections where needed.
- Review permits and shoreline limitations.
- Compare the home with at least two realistic alternatives.
The best Southampton waterfront second home should function as a real property, not merely a beautiful escape. When access, risk, upkeep, financing, and everyday fit remain sensible after the first view becomes familiar, buyers are more likely to enjoy the home for years to come.